Restaurant and food service

Health insurance for restaurant owners.

Long hours, tight margins and staff turnover make benefits hard to plan. We compare individual plans for you and look at what makes sense for your team.

5.0 rating · 26 Google reviews
Free quote

Get your free quote

Enter your ZIP code to see plans in your area.

Free quote. We'll call to go over your options.

What's different for you

Buying insurance as one of Florida restaurant owners

Running a restaurant leaves little time to shop for insurance, so owners often go without or keep a plan that no longer fits.

We look at two questions separately: what coverage you need as an owner, and whether offering something to your staff is realistic.

You, the owner

Individual Marketplace and private PPO plans, compared with your real income and doctors.

Offering coverage to staff

A traditional group plan or a reimbursement approach. Rules and costs differ, so we walk through each one.

Variable hours and turnover

Group plans often have participation and eligibility rules. We help you understand how they'd apply to your schedule.
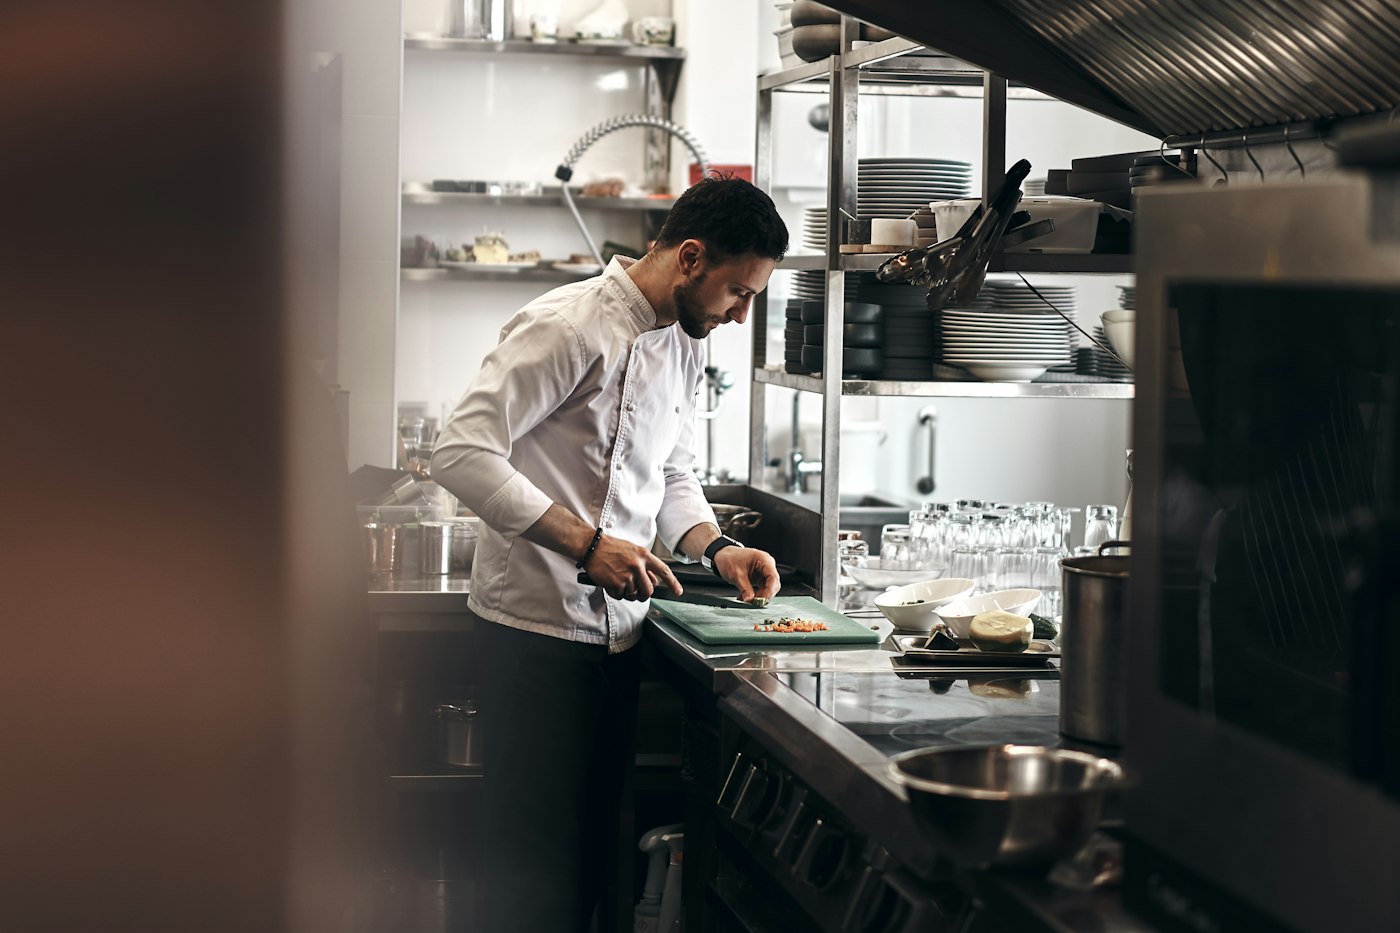
A chef working in a restaurant kitchen
Two main options

Marketplace or private PPO?

Most people working for themselves choose between two kinds of plans. They work differently, and we compare both with your real numbers.

ACA Marketplace plans

Accept everyone regardless of health history, cover a standard set of benefits, and can come with premium help that depends on your income.

Private PPO plans

Often have broader doctor networks and some options with no deductible. They ask health questions and can limit or exclude coverage. Some aren't ACA-compliant, so we go through exactly what's covered.

Read more: Private PPO vs. ACA Marketplace plans and how to estimate your income.

Many self-employed people can deduct health insurance premiums on their taxes. Ask your tax professional how that applies to you.

Questions

Common questions

Do I have to offer health insurance to my employees?

Federal rules that require employers to offer coverage generally apply to employers with about 50 or more full-time equivalent employees. For most small restaurants it's a choice. We can help check what applies to you.

Can I get a group plan if I only have a few employees?

Often yes, if you have at least one employee who isn't an owner or the owner's spouse, though carriers set their own participation rules.

What about my own coverage?

As an owner you can compare individual plans, and many owners can deduct premiums. Ask your tax professional how that applies to you.

Keep reading

Other professions and guides

Free quote

Talk to Julian.

Call or start a quote and we'll go through your options with you. Open seven days a week during open enrollment, 8 AM to 8 PM.

Start a quote